info@stockbinge.com.au
 03 8609 4895

Report
- Megaport Limited ASX-MP1
Megaport Limited ASX-MP1
| Megaport Limited | Team StockBinge | 4-May-2026 | ASX:MP1 |
Recommendation: Buy | Sector: Technology
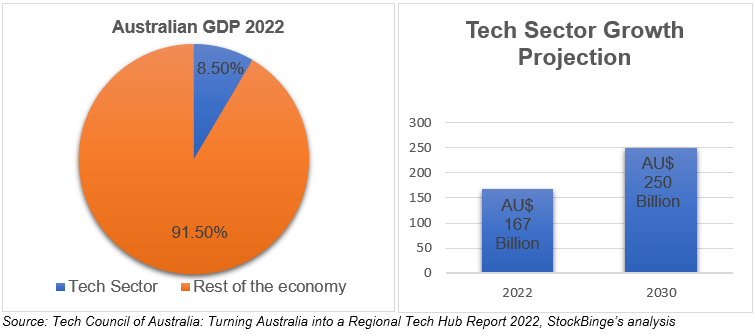
Australian Technology Market
Australia has emerged as a leading hub for digital technology innovation, with a tech industry valued at approximately $167 billion, having grown ~80% over the past five years. The ecosystem is highly diverse and investment-ready, supported by strong capabilities across SaaS, fintech, cybersecurity, quantum computing, digital gaming, and other advanced technology solutions with growing global relevance. Australia’s technology sector is dynamic and highly entrepreneurial, fostering global leaders such as Canva, Atlassian, and WiseTech, alongside numerous unicorn start-ups. Strength comes from collaboration between universities, government, and industry within advanced technology hubs, combining world-class research with a thriving start-up culture that scales ideas into commercially viable products. Government support—through incentives, grants, and targeted funding programs—sustains growth, while a stable regulatory framework ensures a secure environment for long-term innovation and investment.
In addition, Australia continues to attract significant investment from global technology leaders such as Google, Amazon, Microsoft, BT, NEC, and Cisco, supported by its highly skilled workforce and mature innovation ecosystem. The country’s strategic position as a gateway to the Asia–Pacific region, together with strong regional trade relationships, provides technology companies with compelling expansion opportunities and access to international markets. Together, these factors make Australia a highly attractive destination for technology investment, offering scalable, innovative opportunities underpinned by rapid growth, strong government backing, and deep technical talent.
The technology sector is growing at an average annual rate of 16%. If considered as a single industry, technology ranks as the third-largest industry in Australia. Business software, biotech, medical devices, media & design, and PayTech are each technology sectors valued at A$30 billion.
Australia’s Rankings in IMD World Digital Competitiveness 2022
| Category | Ranking | Description |
| Country Credit Rating | 1st | Signifies Australia’s solid economic strength and international credit reliability. |
| Software Piracy Controls | 5th | Highlights robust digital security and measures against software piracy. |
| Regulatory Framework for Starting a Business | 5th | Indicates effectiveness and backing for the establishment of new enterprises. |
| Stable Regulatory Environment | 5th | Shows a consistent and reliable legal framework supporting economic growth. |
Source: Australian Trade and Investment Commission, StockBinge’s analysis
Technology and Market Trends- Australia 2025 (Source: Australian Tech Leaders Survey 2025)
1. The defining technology trends of 2025 include: Artificial Intelligence (AI): Driving automation, innovation, and corporate efficiency, Cybersecurity: Growing digital threats have made cybersecurity a top priority across all industries, and Sustainability & Circular Technologies: Gaining prominence as businesses adopt eco-friendly and resource-efficient models.
2. Australia’s Digital Market Ranking: Australia is ranked 4th globally as one of the most desirable online consumer markets, indicating its solid digital infrastructure, high internet penetration, and tech-savvy population.
3. Online Shopping Behaviour: According to a recent study, 82% of Australian households now shop online, highlighting the country's robust e-commerce adoption and high level of consumer confidence in digital platforms.
According to KPMG Australia’s 2026 “Keeping Us Up at Night” survey, 63% of 274 surveyed executives identified AI and new technologies as their top concern for 2026, reflecting a shift toward AI implementation and ethical risks as key business challenges. The survey shows that this concern dominates both immediate priorities and the 3–5 years’ outlook.
Key Findings from the KPMG 2026 Report:
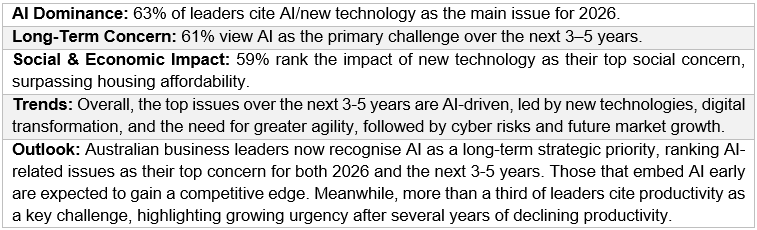
The survey confirms that AI is no longer a niche concern but a central, long-term strategic priority for Australian businesses.
Tech Talent in Australia
Australian cities possess a deeper and more experienced pool of technology professionals compared to many other global tech hubs.
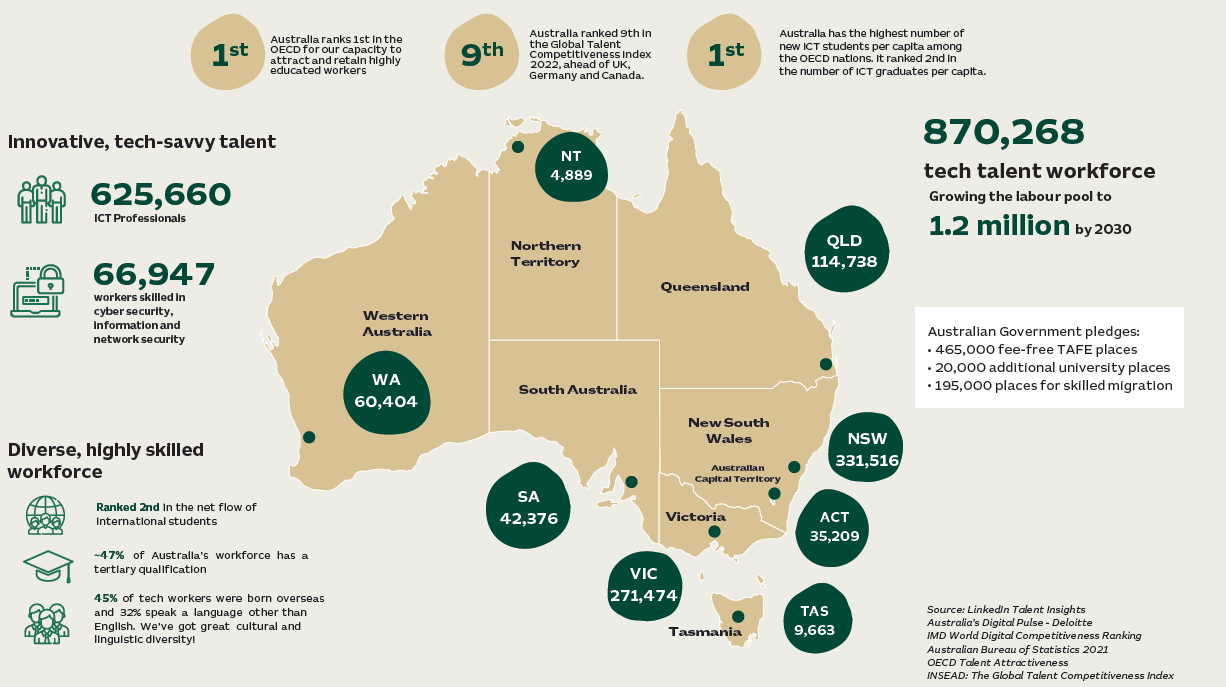
(Source: Australian Trade and Investment Commission)
The Australian government’s strong support for digital investment
The Australian Government is actively supporting digital investment and technology innovation through a range of initiatives. The $15 billion National Reconstruction Fund (NRF) includes $1 billion for critical technologies via loans, equity, and guarantees, while the $9.9 billion Cyber Security Fund and REDSPICE programme aim to strengthen national cyber capabilities and unlock a $5 billion growth opportunity for the cybersecurity sector.
Tax incentives further boost innovation and adoption. Employee Share Schemes (ESS) support talent retention, the Technology Investment Boost offers small businesses a 20% deduction on eligible digital expenses, and the R&D Tax Incentive (RDTI) provides offsets for research and development. Additionally, the Quantum Strategy accelerates the development and commercialisation of quantum technologies, positioning Australia as a global leader. These measures collectively foster innovation, drive digital transformation, and strengthen Australia’s competitiveness in critical tech sectors.
About the Company:
Megaport Limited (ASX: MP1) is an Australia-based Network as a Service (NaaS) company transforming how businesses connect their digital infrastructure. Founded in 2013 and headquartered in Fortitude Valley, the company delivers on-demand interconnection services through its global Software Defined Network (SDN) platform. This technology enables enterprises to seamlessly link data centres, cloud environments, and network services using a simple, user-friendly portal or open API. The company’s platform is designed to provide secure, scalable, and flexible connectivity, allowing customers to establish private, high-performance connections within minutes. Its key offerings include Megaport Internet Port, Virtual Cross Connects (VXCs), Megaport Cloud Router (MCR), Megaport Virtual Edge, and Firewall as a Service (FWaaS), among others. These solutions support a wide range of use cases such as hybrid cloud, cloud-to-cloud connectivity, global wide area networks (WAN), and data centre interconnects. Operating across major global markets, including Australia, North America, Asia-Pacific, and Europe, Megaport has built a vast ecosystem spanning over 1,000 enabled locations. The company collaborates with leading cloud providers, data centre operators, and managed service partners, reinforcing its position in the rapidly growing cloud connectivity space. With ISO/IEC 27001 certification, Megaport emphasizes security and reliability while enabling businesses to build agile, future-ready network infrastructure.
| Risk | Low to Medium |
| Market Cap (AU$) | 1.62b |
| Shares Outstanding | 177.86m |
| Beta | 1.18 |
| EPS (TTM) | -$0.127 |
| PE (TTM) | - |
| Dividend Yield | - |
| 52 Week Range (AU$) | 6.400 – 17.870 |
| Target Price (AU$) | 15.000 |
| Stop Loss (AU$) | 6.650 |
Stock Performance Profile:
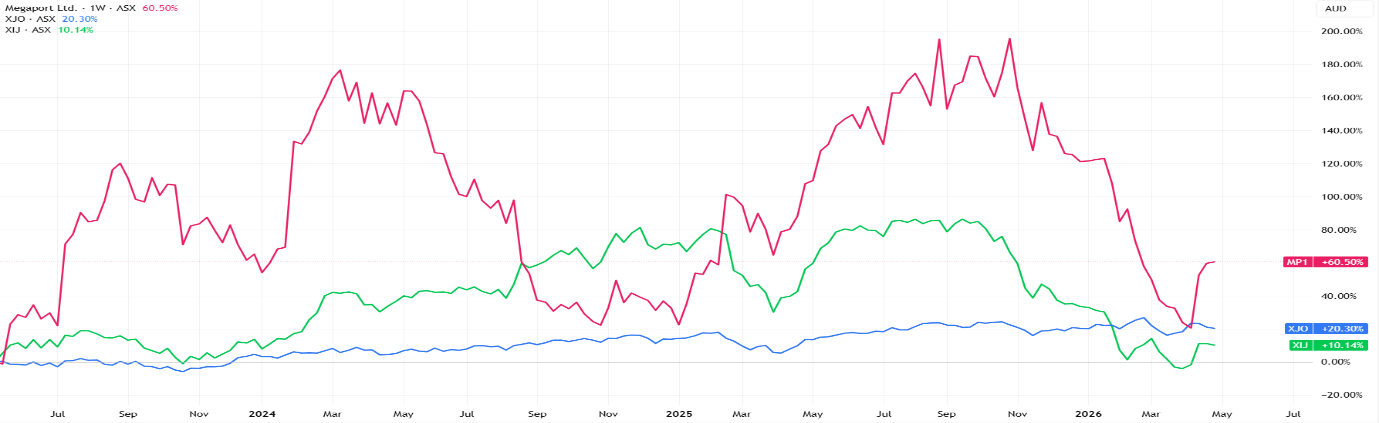
Source: Trading View
Financial Summary:
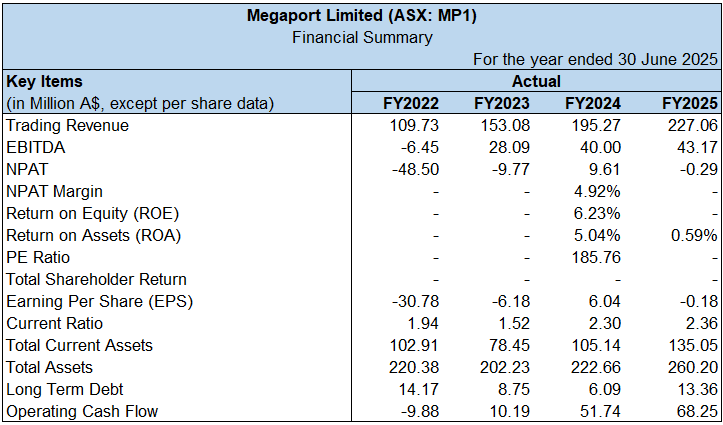
Source: Company filings, StockBinge’s Analysis
Megaport Limited (ASX: MP1) delivered solid top-line growth in FY2025, with trading revenue increasing to $227.06 million from $195.27 million in FY2024. This continued revenue expansion highlights sustained demand for the company’s network connectivity and cloud services offerings. EBITDA also improved further to $43.17 million, up from $40.00 million in the previous year, reflecting stronger operational efficiency and ongoing scale benefits across the business. Despite the improvement in operating performance, the company reported a small net loss after tax (NPAT) of $0.29 million in FY2025 compared with a profit of $9.61 million in FY2024. As a result, earnings per share declined to a loss of 0.18 cents from positive EPS of 6.04 cents a year earlier. Return on assets also eased to 0.59%, indicating weaker profitability relative to the company’s asset base during the period. Financially, the balance sheet remained stable. Total assets increased to $260.20 million, while current assets rose strongly to $135.05 million. Liquidity improved further, with the current ratio strengthening to 2.36 from 2.30 in FY2024, suggesting the company remains well-positioned to meet short-term obligations. Operating cash flow improved significantly to $68.25 million, demonstrating strong cash generation despite softer bottom-line profitability.
First Half (H1) FY2026 Financials:
Megaport Limited (ASX: MP1) reported a record performance in H1 FY2026, driven by strong growth in its core network business and the successful execution of two strategic acquisitions. Group Annual Recurring Revenue (ARR) increased 49% year-on-year to $338 million, reflecting both organic expansion and contributions from recently acquired businesses. Excluding acquisitions, ARR grew 19% in constant currency terms, supported by strong customer additions, higher product adoption, and improved customer retention. Net Revenue Retention strengthened to 111%, while customer lifetime extended from 10 to 13 years, lifting customer lifetime value by 57% to $2.5 billion in constant currency terms. Revenue for the half reached $134.9 million, up 26% on H1 FY2025, including $129.1 million from the Megaport Network business and an initial contribution from the newly acquired Latitude.sh platform. EBITDA for the period was $35.3 million, highlighting continued operational strength despite significant investment activity during the half. The company completed the acquisitions of Latitude.sh and Extreme IX, expanding its presence in compute, GPU-as-a-service, and the Indian market. To support these initiatives and future growth opportunities, Megaport also completed a successful capital raise of $218.2 million. Underlying net loss for the period was $3.3 million, excluding acquisition-related costs of $15.8 million. Management remains confident in growth momentum and has raised the lower end of its Megaport Network revenue guidance while reaffirming Latitude.sh revenue expectations.
Risk Analysis
Megaport Limited (ASX: MP1) faces a broad range of operational, financial, and strategic risks that could affect its long-term growth and profitability. One of the company’s key risks is information security and privacy breaches, as Megaport operates a global network infrastructure handling sensitive customer and operational data. Any cyberattack, data breach, or system compromise could disrupt services, damage customer trust, and lead to regulatory penalties and reputational harm. The company is also highly dependent on the reliability of its network infrastructure and third-party technology providers. Major hardware, software, or network failures caused by cyber incidents, human error, natural disasters, or power disruptions could negatively impact service delivery and customer retention. In addition, Megaport operates in a highly competitive industry where large telecommunications providers, data centre operators, and emerging technology competitors may challenge its market position through stronger financial resources, bundled offerings, or new connectivity technologies.
Megaport’s expanding international operations expose it to regulatory compliance, foreign exchange, and tax-related risks across multiple jurisdictions. Adverse regulatory changes or tax assessments could increase compliance costs and affect profitability. The company also depends on attracting and retaining highly skilled employees in specialised technology roles, making talent retention critical to ongoing innovation and execution. Furthermore, weaker global economic conditions, customer churn due to flexible contract structures, and potential non-renewal of key infrastructure agreements could pressure revenue growth and operational stability in the future.
Outlook
Megaport Limited (ASX: MP1) enters the remainder of FY2026 with a positive outlook, supported by strong underlying demand across its network connectivity and infrastructure platforms. Management has upgraded the lower end of its core Megaport Network revenue guidance in constant currency, reflecting continued momentum in customer growth, higher net revenue retention, and increasing adoption of larger bandwidth solutions and long-term contracts. The company’s strong performance in the United States and broader Americas region is expected to remain a key contributor to future ARR growth. The acquisitions of Latitude.sh and Extreme IX are expected to expand Megaport’s exposure to high-growth markets including compute infrastructure, GPU-as-a-service, AI workloads, and the rapidly growing Indian digital infrastructure market. Management believes the integration of network and compute capabilities will strengthen the company’s competitive positioning and create additional cross-selling opportunities across enterprise customers globally.
For FY2026, Megaport expects group revenue between $302 million and $317 million, with EBITDA margins projected at 21% to 24% of revenue. The company also plans targeted capital investment to support infrastructure deployment and expansion initiatives, particularly across India and Megaport Compute services. While foreign exchange volatility remains a headwind, management remains confident that disciplined capital allocation, scalable infrastructure, and ongoing product innovation will support sustainable long-term growth across network, compute, and AI-related services.
Stockbinge’s Forecast
Megaport Limited is expected to deliver steady revenue growth over the next two to three years, supported by demand for network connectivity, AI-related workloads, and contributions from acquisitions such as Latitude.sh and Extreme IX. Analyst estimates suggest revenue could grow at around 23.3% annually, reaching approximately $312 million in FY2026, $433 million in FY2027, and $542 million in FY2028, broadly in line with company guidance. This outlook is supported by H1 FY2026 performance, including ARR growth to $338 million, along with stable customer retention and improving lifetime value.
Profitability is projected to improve gradually, with earnings moving from a modest loss in FY2026 to positive territory in FY2027 and FY2028. This reflects operating leverage and scale benefits, with earnings and EPS expected to grow steadily, supporting a return on equity of around 12.7% by FY2028. Growth drivers include expansion in the Americas, entry into India through Extreme IX, and increasing adoption of compute and GPU services. While competition, cybersecurity risks, and currency fluctuations remain factors to monitor, the company expects EBITDA margins in the range of 21–24% for FY2026 with planned investments.
Technical Analysis
Source: Trading View
StockBinge’s View:
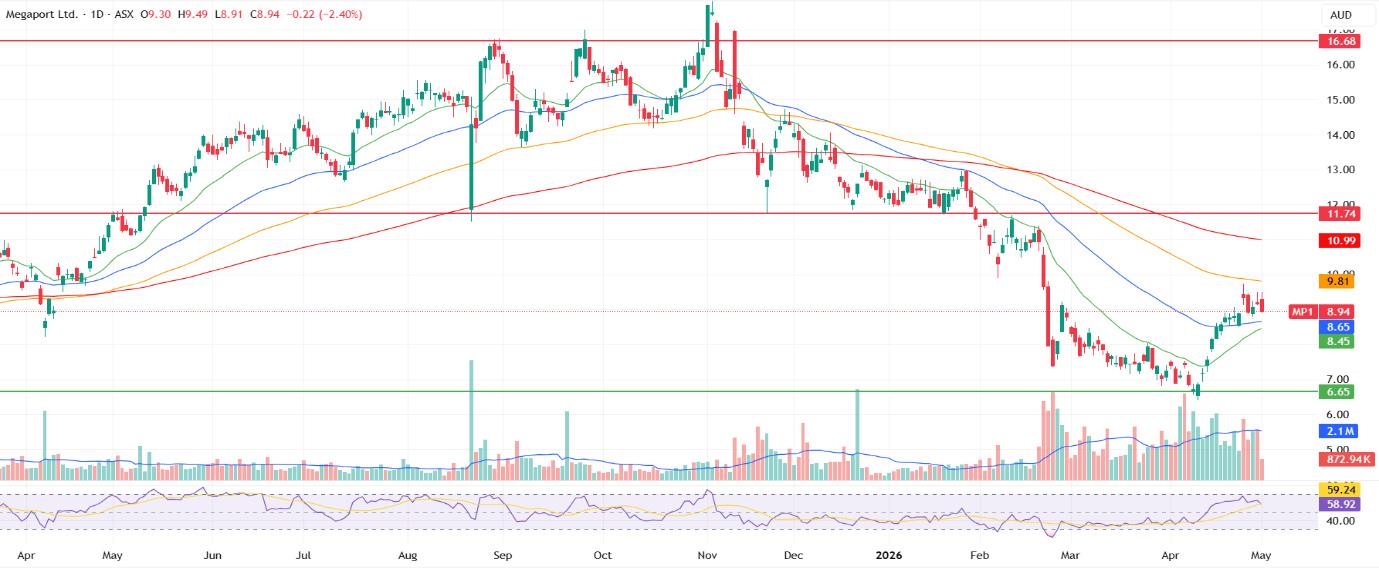
Megaport Limited enters the second half of FY2026 with strong momentum, supported by rising customer demand, improving retention rates, and continued growth in larger bandwidth deployments and long-term contracts. The company expects strong growth in the United States and broader adoption of its network, compute, and AI infrastructure solutions. Recent acquisitions, including Latitude.sh and Extreme IX, are expected to expand Megaport’s market opportunity and create cross-selling benefits across connectivity and compute services. Backed by a strengthened balance sheet following its capital raise, the company remains well-positioned to invest in expansion, innovation, and long-term recurring revenue growth. Technically, Megaport Limited (ASX: MP1) remains in a broader downtrend, although the stock has recently shown signs of short-term recovery after rebounding strongly from the major support zone near $6.65. The recent rally has helped the share price reclaim its 20-day EMA around $8.45 and move above the 50-day EMA near $8.65, indicating improving near-term momentum and a potential shift in short-term sentiment. However, the stock continues to trade below its longer-term 100-day and 200-day EMAs. A sustained move above the long-term EMA and resistance near the $11.740 region would strengthen bullish momentum. Momentum indicators are improving, with the RSI rising around 60, suggesting strengthening buying momentum without yet reaching overbought territory. Volume activity has also increased during the recent rebound, indicating renewed investor participation and improving market confidence in the stock’s recovery attempt. StockBinge recommends a “Buy” at the closing price of 8.940 (as of 01 May 2026) with a stop loss of $6.650 for the target of $15.000.
Disclaimer:Stockbinge Pty Ltd (ACN: 672 177 347) is a Corporate Authorised Representative (CAR No 001309039 of Titan Securities Pty Ltd (AFSL no 307040). Under these authorisations, Stockbinge is authorised to provide general financial product advice to retail clients in respect of certain classes of financial products, which include securities, government bonds, and debentures. Any financial product advice provided is general advice only and does not take into account your personal objectives, financial situation, or needs. Stockbinge provides stock research reports, which may include factual information and general financial product advice about securities and debentures. Securities trading involves a high level of risk and may not be suitable for all investors. You should obtain personal financial advice from a licensed financial adviser before making any investment decisions. Past performance is not indicative of future results. For further details, please refer to our Financial Services Guide (FSG) available on our website.
- Download Report:
- Download
ABN 54 672 177 347 | ACN 672 177 347
Copyright © 2026 StockBinge. All Right Reserved. Design by StockBinge.